September 28, 2026
In this article
- What You Will Learn From This Blog
- What Are Banking Transaction Classification Categories?
- Common Banking Transaction Classification Categories
- How to Choose the Right Category for a Banking Transaction
- Common Banking Transaction Classification Mistakes
- What Is Automated Transaction Classification?
- CashBooks for Automated Transaction Classification
- Our Expert Insight
- Key Takeaways
- FAQs
Every bank transaction tells part of a business’s financial story. But a bank feed alone does not show whether a payment is income, an expense, a transfer, a loan payment, or another type of activity. Each item needs the right place in the books.
Using clear banking transaction classification categories helps keep financial records clean and easy to review. It also makes reports more useful at month-end and gives business owners and bookkeepers a better view of where money comes from and where it goes.
The goal is not to sort every item as fast as possible. The goal is to put each transaction in the right account, keep the same rules over time, and review items that need a closer look. This is where automated transaction classification can help with routine work while leaving final judgment to the person managing the books.
What You Will Learn From This Blog
- What banking transaction classification categories are and why they matter
- Common categories used for business bank transactions
- How to choose the right category for each transaction
- Common errors that can lead to poor financial records
- How automated transaction classification can reduce repeat work
- Where human review still matters in the bookkeeping process
What Are Banking Transaction Classification Categories?
Banking transaction classification categories are the account types used to sort activity from a business bank account. A transaction is placed into a category based on what the money was for and how it should appear in the accounting records.
For example, a payment to a software vendor may belong to a software expense account. A payment from a customer may be recorded as sales income. A move of cash from checking to savings is not normally income or an expense. It is a transfer between accounts.
The right category depends on the business, its chart of accounts, and the reason for the transaction. Two businesses may use different account names for similar activity. What matters is that the system is clear and used in a steady way.
Good classification also helps with reporting. When expenses are placed in the right accounts, a profit and loss report can show where the business spends money. Income can be tracked by the right source, while transfers and other non-income activity stay out of sales totals.
Common Banking Transaction Classification Categories
The exact account list will vary by business, but several banking transaction classification categories are common across small businesses and firms.
1. Income and Sales
Money received from customers is often recorded as sales or service income. The exact account can depend on what the business sells.
For example, a design firm may track design services as service income. A store may use sales income for product sales. Keeping income in the right account helps make revenue reports more useful.
2. Operating Expenses
Operating expenses cover the normal costs of running a business. Common examples include:
- Office supplies
- Software
- Advertising
- Rent
- Utilities
- Insurance
- Professional services
- Phone and internet costs
A business may use separate accounts for these costs when it needs more detail in its reports.
3. Payroll and Employee Payments
Payroll-related transactions may include wages, benefits, payroll taxes, and other employee costs. These should be kept in the proper accounts so labor costs are not mixed with general operating expenses.
The exact treatment can depend on the payroll system and the business's accounting setup.
4. Transfers and Owner Transactions
Transfers between business bank accounts should not be treated as income or expenses. The same applies to certain owner contributions and draws.
For example, moving $5,000 from a checking account to a savings account does not create $5,000 of new income. It only moves cash between accounts.
This is one of the areas where careful classification matters. A transfer recorded as income can make revenue look higher than it really is.
5. Loan Payments and Financing
Loan activity may include principal payments, interest, loan proceeds, and related fees. These items may need different accounts because they do not all have the same effect on the books.
A loan payment, for example, can include both principal and interest. Treating the full payment as one expense can lead to incorrect records.
6. Bank Fees and Interest
Bank service fees, wire fees, merchant fees, and interest income are often tracked in separate accounts.
These transactions may be small, but they can add up over time. They also tend to occur on a regular basis, which makes them good candidates for consistent rules.
7. Taxes and Government Payments
Tax payments may include sales tax, payroll tax, estimated tax payments, and other government charges. Their treatment depends on the type of tax and the business's accounting method.
These transactions deserve extra care because a wrong category can affect both reports and tax records.
8. Refunds and Returns
Customer refunds, vendor refunds, and returned payments should be classified based on what they relate to. A refund is not always a new expense or a new source of income.
The original transaction and the related refund should make sense when reviewed together.
How to Choose the Right Category for a Banking Transaction
Choosing between banking transaction classification categories starts with understanding what the transaction actually represents.
Start with the bank description. It can show the vendor, customer, payment type, or other clues. But the description alone may not be enough.
Next, check the vendor or customer. A payment to a known software company may be easy to classify, while a payment with a vague description may need more detail.
Past transactions can also help. If the same vendor has been reviewed many times and always belongs to the same account, that history can support a consistent choice.
Supporting records are useful when the transaction is unclear. An invoice, receipt, bill, or other business record can show what the payment was for.
For larger, new, or unusual transactions, do not rely only on a description or an old rule. Review the source record before making the final choice.
Common Banking Transaction Classification Mistakes
Even a well-run bookkeeping process can have classification errors. Some of the most common problems include:
Treating Transfers as Income or Expenses
Transfers between accounts can look like deposits or withdrawals in a bank feed. If they are classified as income or expenses, financial reports may be overstated.
Using One Broad Account for Everything
A business may be tempted to put many different costs into a single expense account. While this can save time, it can make reports less useful when the business needs to see where its money is going.
Mixing Personal and Business Spending
Personal purchases made from a business account can create problems if they are recorded as business expenses. These items should be handled based on the business's accounting setup and owner transaction rules.
Trusting Every Repeat Pattern
A vendor may normally be coded to one account, but that does not mean every payment from that vendor has the same purpose. A new type of charge can require a different category.
Skipping Review
Automation can help sort routine activity, but unclear transactions still need attention. A process with no review step can allow small mistakes to build up over time.
What Is Automated Transaction Classification?
Automated transaction classification uses software rules, transaction data, past choices, or AI to suggest or assign categories to bank activity.
Instead of manually deciding the account for every transaction, the system can identify patterns in routine activity. A recurring software charge from a known vendor, for example, may be assigned to the same expense account based on prior activity.
Some systems can also use business rules and a chart of accounts to improve their suggestions. AI-based tools may look at more than the bank description and use past classification choices to make a more useful suggestion.
The key point is that automation should support the bookkeeping process rather than remove the need for judgment.
A good process can look like this:
Bank feed → Transaction classification → Review checks → Human review → Reconciliation
Routine items can move through the process with less manual work. New vendors, high-value payments, odd charges, and unclear items can be sent for review.
This approach can help reduce repeat data entry while keeping a person involved when the reason for a transaction is not clear.
CashBooks for Automated Transaction Classification
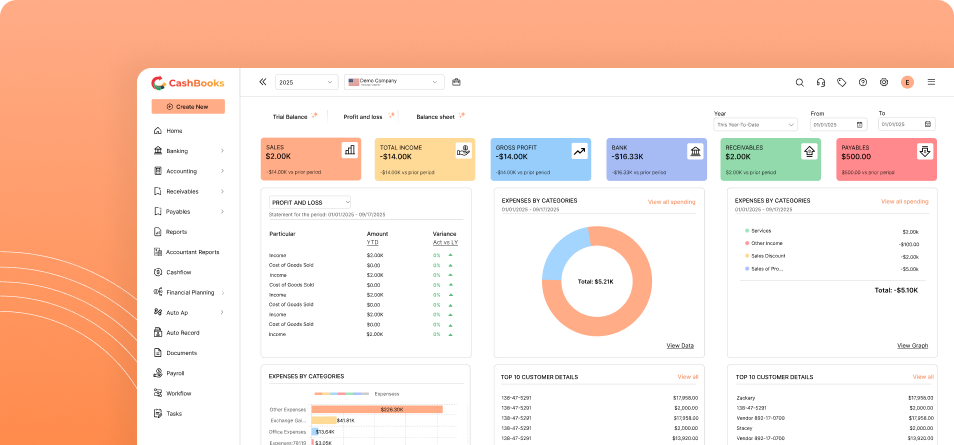
CashBooks helps businesses keep bank transactions organized from the moment they enter the books through final review. The focus is not just on automation, but on making each step easier to check.
Capture and Categorize
Smart Bank Feeds bring in new bank activity, while AI Transaction Categorization uses past choices, business activity, and rules to suggest the right account.
Review What Needs Attention
The Review Engine flags unusual, duplicate, or missing entries. Users can check the suggested category and change it when needed.
Reconcile and Report
Suggested Reconciliation Matches help match bank activity with recorded transactions. Accountant Reports make it easier to share organized records with bookkeepers and accounting firms.
With these tools in one workflow, CashBooks helps reduce repetitive classification work while keeping important accounting decisions under human review.
Our Expert Insight
Good transaction classification starts with the reports a business needs. If management wants to track software, travel, or bank fees separately, those costs should not all go into one broad expense account.
Review the categories at least once in a while. Check for vendors being coded to different accounts, expenses that are too broad, and categories that no longer fit the business.
With automated transaction classification, accuracy matters more than the number of transactions processed. A good system should make routine work easier while letting a bookkeeper quickly review and correct entries when needed.
Key Takeaways
- Clear banking transaction classification categories help keep financial records organized.
- Income, expenses, transfers, loans, fees, taxes, and refunds may need different accounts.
- The right category depends on the purpose of the transaction and the business's chart of accounts.
- Bank descriptions can help, but they may not give enough detail on their own.
- New, large, and unusual transactions should receive closer review.
- Automated transaction classification can reduce repeat manual work.
- Human review still matters when a transaction does not clearly fit an existing rule.
- Consistent classification supports cleaner reports and easier reconciliation.
FAQs
1. What is the difference between transaction classification and reconciliation?
Classification assigns a transaction to the right account. Reconciliation checks whether the books match the bank's records.
2. How should credit card payments be classified?
A credit card payment is generally recorded as a payment toward the card balance, not as a new expense. The original purchase is what creates the expense.
3. Should bank transfers be classified as income?
No. Transfers between a business's own accounts are not new income and should be recorded as transfers.
4. Can transaction categories be changed later?
Yes. A transaction can be recategorized if a review shows that the original account was incorrect. The new category should match the transaction's actual purpose.
5. How often should transaction categories be reviewed?
A monthly review works well for many small businesses. It can catch inconsistent coding and new expenses before reports are finalized.